ROCHESTER MA— Rochester property owners will see a minor uptick in their local tax rates following the Select Board’s decision to approve a uniform property tax rate of $10.62 per $1,000 of assessed value for the upcoming fiscal year.
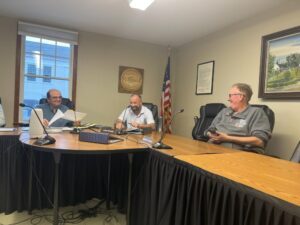
The decision came during the Select Board’s meeting on Monday, Sept. 21, following a formal tax classification presentation by Director of Assessing Karen Trudeau. The newly adopted rate represents an increase of 3 cents per $1,000 of assessed property value compared to the previous tax year. Under the approved framework, the $10.62 rate will apply equally across all property classifications, keeping residential and commercial property owners on an identical tax footing.
Maintaining a Uniform Tax Rate
In Massachusetts municipal finance, communities must evaluate annually whether to adopt a single tax rate across all real estate classes or implement a “split tax rate.” A split rate shifts a higher percentage of the local tax burden onto commercial, industrial, and personal property owners to lessen the tax load on residential homeowners.
Trudeau advised the board to maintain Rochester’s long-standing policy of a single, unified rate. In primarily residential and agricultural communities like Rochester, where the commercial tax base represents a smaller fraction of overall town valuation, attempting to split the rate often places a heavy financial strain on local small businesses while offering only negligible savings to residential taxpayers. By maintaining a uniform rate, the town continues to provide predictable tax conditions for local commercial enterprises, farms, and residents alike.
Board Rejects Tax Exemptions and Open Space Discounts
During her presentation to the board, Trudeau addressed several optional tax relief mechanisms allowed under state law, recommending against the adoption of each.
First, Trudeau recommended against adopting an open space discount. Under Massachusetts tax regulations, municipalities can grant a reduced tax rate to land formally classified as open space. However, granting a discount reduces the taxable valuation from those specific parcels, requiring the remaining property owners in town to absorb the difference.
Second, Trudeau recommended against implementing a residential exemption or a small commercial exemption. A residential exemption reduces the taxable value of primary residences—benefiting lower-valued homes while shifting the difference onto higher-valued properties, secondary homes, and rental units. A small commercial exemption provides targeted relief to small businesses occupying commercial properties valued below a state-established threshold.
The Board of Assessors has historically taken a firm stance against these measures, a position Trudeau reiterated directly to the Select Board.
“The Board of Assessors has never recommended the town provide exemptions because it just raises the taxes and it shifts the burden to other classes,” Trudeau said.
Because municipal tax levies are calculated to cover fixed town operating costs—including public schools, emergency services, highway maintenance, and municipal infrastructure—exemptions do not reduce the total amount of tax revenue the town must collect. Instead, exemptions reallocate that financial burden among different groups of taxpayers.
Local Impact and Tax Rate Certification
For the average Rochester homeowner, the 3-cent increase per $1,000 of valuation represents a modest adjustment on annual property tax statements. For instance, on a home assessed at $500,000, a 3-cent increase amounts to an additional $15 per year in property taxes attributable directly to the rate adjustment, baseline valuation changes notwithstanding.
Following the Select Board’s formal approval, the town’s assessing department will submit the tax classification documentation and tax recap sheet to the Massachusetts Department of Revenue (DOR) Division of Local Services for final review and certification. Once certified by state officials, the updated $10.62 rate will be used to calculate final tax bills for the fiscal year.
Join the Plimoth Y2K Usenet Discussion
Engage with local readers, share community stories, and browse threaded community bulletin boards in our classic web forum.